Market overview and structural significance of the Craniotomy Power Systems Market
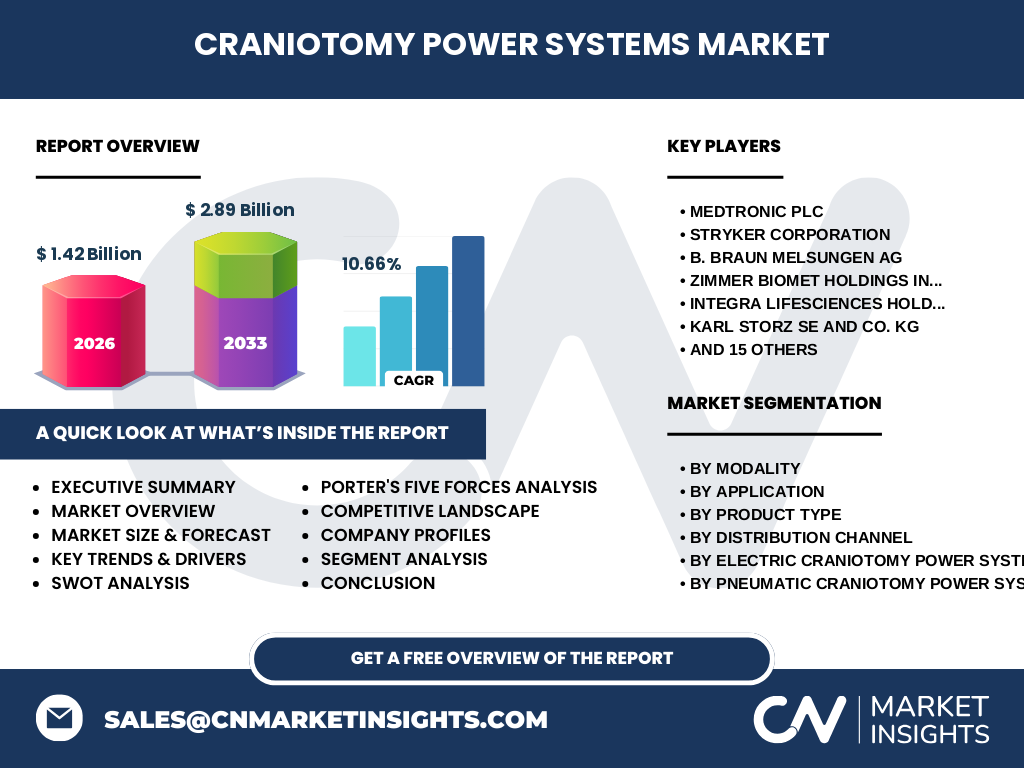
Our analysis indicates that the Craniotomy Power Systems Market represents a critical surgical technology sector valued at 1.42 Billion in 2026. This market encompasses specialized electric, pneumatic, and battery-powered instruments essential for neurosurgical and trauma procedures, requiring rigorous compliance with regulatory bodies like the US FDA and European MDR.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Craniotomy Power Systems Market?
The market is driven by rising neurological disorder prevalence and technological advancements in surgical precision. However, high equipment costs and stringent sterilization compliance act as key restraints. Opportunities abound in emerging markets as ambulatory surgical centers expand, though supply chain bottlenecks for medical-grade raw materials pose ongoing operational challenges.
Emerging trends and growth patterns in the Craniotomy Power Systems Market
The shift toward cordless ergonomics and lithium-ion powered surgical systems is redefining operating room efficiency. Manufacturers are prioritizing brushless motor technologies to minimize thermal necrosis during high-speed cranial drilling, directly addressing clinical demands for safer, more versatile instrumentation.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted elective neurosurgeries, leading to a temporary contraction in equipment procurement. Recovery has been robustly propelled by hospital capital budget reinstatements and a procedural backlog, favoring established players with resilient global distribution networks capable of navigating ongoing logistical hurdles.
Competitive Benchmarking and strategic dynamics
Market concentration is moderately high, dominated by multinational medtech giants alongside specialized innovators. Companies like Medtronic plc and Stryker Corporation leverage expansive portfolios, whereas specialized firms such as Bien-Air Surgery SA and ADEOR Medical AG focus on niche high-speed drilling innovations.
Executive Summary of the Craniotomy Power Systems Market research findings
Driven by technological convergence and an aging global demographic, the Craniotomy Power Systems Market industry trends point toward sustained expansion. The market is projected to reach 2.89 Billion by 2033, expanding at a robust CAGR of 10.66% from 2027 to 2033.
Long-term market forecast from 2027 to 2033
Based on our econometric modeling, the market will scale aggressively from its 2026 baseline to achieve 2.89 Billion by 2033. This trajectory is underpinned by a steady 10.66% CAGR, fueled by rising surgical volumes and hospital investments in next-generation integrated surgical systems.
Segmentation Analysis across modalities, applications, product types, and distribution channels
The market segments into modalities (standalone and integrated systems), applications (neurosurgery, trauma surgery, ENT), product types (electric, pneumatic, battery-powered), and distribution channels. Neurosurgery and electric-powered systems capture dominant revenue shares due to their clinical indispensability in complex cranial procedures.
Regional market analysis and geographic distribution performance
North America maintains revenue dominance due to advanced healthcare infrastructure and high adoption rates of advanced surgical tech. Meanwhile, Asia-Pacific exhibits the fastest regional growth, propelled by expanding hospital investments in countries like China and Japan, supported by local innovators such as Chongqing Xishan Science And Technology.
In-depth regional review of key markets
North American growth is anchored by strict reimbursement frameworks and high trauma volumes, whereas European markets emphasize stringent CE mark compliance. In the APAC region, localized manufacturing and rising healthcare expenditure are accelerating adoption rates across tier-1 metropolitan neurosurgical centers.
Company profiles and strategic positioning of leading market participants
Industry leaders like Zimmer Biomet Holdings Inc., B. Braun Melsungen AG, and Integra LifeSciences maintain competitive moats through comprehensive product portfolios and direct sales channels. Meanwhile, agile European specialists like Gebr. Brasseler GmbH And Co. KG and Nouvag AG compete via precision engineering.
Porter's Five Forces analysis of the Craniotomy Power Systems Market
Bargaining power of buyers is moderate due to consolidated hospital group purchasing organizations, while supplier power remains low given strict raw material specifications. Competitive rivalry is intense, compelling continuous R&D investments among key firms like CONMED Corporation and KLS Martin Group.
SWOT analysis of the Craniotomy Power Systems Market
Strengths include high-precision engineering and established clinical adoption. Weaknesses involve high initial capital expenditure. Opportunities lie in emerging market penetration and cordless ergonomics, while threats encompass stringent regulatory approval delays and economic downturns impacting hospital capital outlays.
Value chain analysis from raw materials to end-users
The value chain initiates with specialty metal and polymer sourcing, progressing to precision CNC machining and motor assembly by component specialists. Finished products flow through direct sales forces or specialized medical distributors to reach neurosurgeons in hospital operating rooms and ambulatory surgical centers.
Investment insights and strategic high-potential areas
High-potential investment zones center on lithium-ion powered surgical systems and portable battery-operated consoles that enhance operating room mobility. Investors should target companies demonstrating strong regulatory pipelines and established relationships with major group purchasing organizations.
Conclusion and key takeaways for stakeholders
The Craniotomy Power Systems Market analysis confirms a lucrative growth corridor reaching 2.89 Billion by 2033. Stakeholders must prioritize R&D in brushless electric and cordless battery platforms to capture shifting hospital preferences toward ergonomic, high-speed surgical precision.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators, trade registry data from major global ports, and primary stakeholder interviews with neurosurgeons, procurement officers, and C-suite executives across leading medtech firms.
Scope of the report, coverage parameters, and limitations
This report covers the global Craniotomy Power Systems Market across defined modalities, product types, applications, and geographic regions from 2026 to 2033. Limitations include macroeconomic unpredictability and varying regional healthcare policy shifts that may influence adoption timelines.
Recent developments in company announcements, product launches, and strategic moves
Recent industry momentum highlights strategic acquisitions and FDA clearances for advanced cordless drills. Market players like Stryker Corporation and Medtronic plc continue to expand their ergonomic portfolios, while firms such as Aygun Surgical Instruments invest in enhanced manufacturing facilities to meet rising global demand.